

Austin Catastrophic Injury Lawyer
We represent people across Austin and Travis County whose injuries will not heal. As an Austin catastrophic injury lawyer, our approach to a catastrophic injury claim under Texas law turns on two questions: what the claim is worth, and what it takes to collect it.
A permanent injury reorders a family’s life long before anyone says the word lawsuit. Learn more about Breeland Injury Law, or contact us at 512-764-3380 to talk about what happened.
Texas sets the categories of damages a catastrophic case can recover. Two more rules decide whether the money reaches the family: how shared fault is counted, and which policies stand behind the person who caused the harm.
Why Austin Families Turn to Breeland Injury Law for a Catastrophic Injury Claim
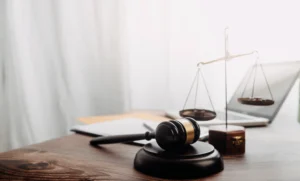
Matt Breeland spent the first eight years of his career on the other side, defending insurance companies against injury claims, before switching in 2016 to represent injured Texans exclusively. That background gives him a clear view of how an insurer will try to undervalue a claim that will follow a family for decades.
As lead trial counsel, Matt obtained one of the top 100 jury verdicts in Texas in 2019, ranking among the state’s top 50 for motor vehicle cases. In 2023, he also ranked in the state’s top 20 for personal injury verdicts overall. Super Lawyers has recognized him as a Rising Star every year from 2017 through 2021 and named him to its main Texas list in 2023 and 2024.
A catastrophic injury case can run for years, and Matt works to keep clients informed at each stage, explaining what a life care plan covers, why a policy limit matters, and what comes next, in plain English. A free consultation is the first step to finding out where a case stands, and the attorney bio page has more on his background.
What Counts as a Catastrophic Injury Under Texas Law?
Texas has no statute that defines a catastrophic injury. In practice the term describes an injury that permanently changes what you can do for work and for yourself. No legal test decides the label.
Three groups of injury dominate these claims:
- Traumatic brain injuries, including losses of cognition and memory
- Spinal cord injuries, with partial or complete loss of function below the injury
- Spine and back injuries where surgery or long-term pain management is recommended
What matters legally is what the damages evidence proves. Section 41.001 of the Texas Civil Practice and Remedies Code sorts recoverable damages into economic and noneconomic categories.
What a Catastrophic Injury Claim Can Recover in Texas
Texas law splits catastrophic injury damages into two kinds: economic and noneconomic. Economic damages cover measurable financial losses tied to the injury, while noneconomic damages cover the physical and personal toll, both broken down in the table below.
| Damage category | What it covers | What proves it |
| Economic | Future medical care, attendant care, equipment, home modifications, lost earning capacity | Life care plan, economic analysis |
| Noneconomic | Physical pain, mental anguish, disfigurement, physical impairment, loss of consortium (marriage relationship), loss of enjoyment of life | Treating providers, family testimony, before-and-after record |
| Exemplary | A penalty, available where the conduct involves fraud, malice, or gross negligence, and capped | Clear and convincing evidence of fraud, malice, or an extreme risk the defendant knew of and disregarded |
Fraud, malice, and gross negligence are three independent grounds for exemplary damages, not stages of one standard. Gross negligence means the defendant actually knew of an extreme risk and went ahead anyway, with conscious indifference to the safety of others. Under Section 41.003 of the Civil Practice and Remedies Code, a claimant must prove one of these three grounds by clear and convincing evidence.
Section 41.008(b) of the Civil Practice and Remedies Code caps exemplary damages at the greater of two figures.
The first is two times economic damages, plus any noneconomic damages the jury finds. No more than $750,000 of that noneconomic amount counts toward the figure. The second figure is $200,000.
How Long Do You Have to File a Catastrophic Injury Lawsuit in Texas?
In Texas you generally have two years to file a personal injury lawsuit. The clock starts on the day the cause of action accrues, which is the day the claim arises.
If the injury caused a death, the two years run from the date of death. Section 16.003 of the Texas Civil Practice and Remedies Code sets both deadlines, subject to the exceptions the statute names.
Legal disability changes the count:
- Section 16.001 of the Texas Civil Practice and Remedies Code pauses the clock. The pause covers the time a person spends under a legal disability that existed when the claim accrued, and the statute defines legal disability as being younger than 18 or of unsound mind.
- A disability that begins after the clock starts does not pause it. Disabilities also cannot be tacked, meaning one cannot be added onto another.
Evidence does not wait for the deadline. Vehicles get repaired and video gets overwritten long before two years run.
How Does Shared Fault Change What You Recover?
You can still recover damages if you were partly at fault. You recover nothing at all once your share of the fault is greater than 50%. Texas calls that rule proportionate responsibility.
Section 33.001 of the Texas Civil Practice and Remedies Code sets that bar for the actions Chapter 33 governs. A 50% share does not cross the line, and any share above that does.
The fault percentage is where the defense spends its money. One point is worth little when damages are small and a great deal when a life care plan runs for decades.
What Happens When the At-Fault Driver’s Policy Will Not Cover a Lifetime of Care?
The next source of payment is usually your own uninsured or underinsured motorist coverage. You turn to that coverage when the at-fault driver’s liability limits are smaller than the cost of your future care. Payment usually arrives in layers:
- The at-fault party’s liability coverage: In a catastrophic case this layer is often gone inside the first year of medical bills.
- Your own uninsured or underinsured motorist coverage: A Texas auto liability policy must carry this coverage under Section 1952.101 of the Texas Insurance Code. The coverage can sit in the policy or be supplemental to it. The one exception is a written rejection by an insured named in the policy. Many Austin drivers hold this coverage without knowing it.
- Other parties who can be named: this may include the commercial carrier behind a truck, the employer of a driver who was working, or a commercial property owner.
Sorting out which layers apply, and in what order, is its own piece of work in a catastrophic claim. If you are unsure which policies stand behind your case, talk with our underinsured motorist coverage team.
When a Catastrophic Injury Becomes a Wrongful Death Claim
If a catastrophic injury results in death, Texas gives the surviving spouse, children, and parents the right to bring a wrongful death action for their exclusive benefit. Under Section 71.004 of the Civil Practice and Remedies Code, any one of them may bring the action for the benefit of all.
The statute names a fallback. If none of them has filed within three calendar months after the death, the estate’s executor or administrator has to bring the action. The exception is when all of them ask otherwise. The deadline is the same two-year period described above, running from the date of death.
Explore Related Practice Areas
A catastrophic injury claim can overlap with other practice areas depending on how the injury happened. You may find these pages useful:
• Truck and commercial vehicle collisions
FAQ: Catastrophic Injury Questions in Austin
What Is a Life Care Plan and Why Does My Case Need One?
A life care plan is a detailed, medically grounded projection of every future cost a catastrophic injury will create: ongoing treatment, equipment, home modifications, and attendant care, priced out year by year for the rest of a person’s life. Insurers rarely accept a rough estimate for a claim this size, so the plan is usually built with input from treating physicians, therapists, and a life care planning specialist. It becomes the backbone of the economic damages evidence described above.
What If the At-Fault Driver Has No Insurance At All?
Even when the at-fault driver has no insurance at all, rather than just too little, your own uninsured motorist coverage still stands as a source of payment, if you carry it. That coverage responds the same way it would to an underinsured driver, just without a first layer of liability coverage to draw from. Whether other parties, like an employer or a property owner, can also be named depends on how the crash happened.
Who Pays for Ongoing Home Health Care After a Catastrophic Injury?
Ongoing home health care is typically paid for out of the settlement or verdict itself, using the future-cost figures a life care plan establishes. It is not paid by an insurer on an ongoing basis after the case closes. That is why proving the true, lifetime cost of care up front matters so much in a catastrophic injury claim. Once a case resolves, that money has to be enough to cover decades of care with no second chance to go back and ask for more.
Talk to an Austin Catastrophic Injury Lawyer
Are you weighing which Austin firm to call about a permanent injury? We offer a free consultation to walk you through what your claim has to prove and what it will take to fund your care. Bring these documents:
- The crash report
- The adjuster’s first letter
- Your own auto policy
The two-year deadline runs from the day the cause of action accrues, but the pieces that prove a case do not last nearly that long. As your Austin catastrophic injury lawyer, call us at 512-764-3380 or contact our team. Learn more about Breeland Injury Law before you call.

I had a great experience working with Matt Breeland. He was professional, responsive, and kept me informed throughout the entire process. He took the time to answer my questions and made everything as smooth and stress-free as possible.
Thank you, Matt, for all your hard work and for helping me through my case. I truly appreciate everything you did and would definitely recommend your services to anyone looking for an attorney they can trust.
After I was rear-ended and unsure how to navigate the legal process, Matt Breeland was recommended to me and I’m really glad he was. He made everything simple and easy to understand, and the whole process ended up being much less stressful than I expected. He handled everything professionally and kept me updated along the way. I also really appreciated the help from his legal assistant, Lisabeth. I’m very grateful for their support and would definitely recommend Matt to anyone who needs a great attorney!
As a foreigner, this was my first time experiencing an car accident here, and I had no idea how the process worked. I felt scared, worried, and overwhelmed. I read many law firm reviews before choosing here, and it turned out to be a perfect decision.
He was incredibly kind, and what I appreciated most was communication. He always reassured me and made me feel at ease throughout the entire process. He handled my case very efficiently and brought everything to a smooth conclusion.
I’ve seen many people around me experience long delays in their settlements, but my case was resolved much sooner than I expected. I truly and sincerely recommend this law firm.
I highly recommend Attorney Matt Breeland and Breeland Injury Law for personal injury legal representation. He and his team provided exceptional guidance and representation for my matter following a car accident in which I was rear-ended at a stop light, my car was totaled, and I sustained injuries for which my doctor expects I will require chronic pain management.
Matt Breeland always made himself available to explain the complex legal concepts of my case, which was instrumental in helping me understand the implications of every decision he and I needed to make. He always communicated in a manner that made me feel supported and informed. And his responsiveness to my calls, texts, and emails was invaluable during critical phases of the process.
Mr. Breeland provided much-needed reassurance throughout the 17 months from our first introduction to settlement with the insurance company for the person who hit me. His commitment to keeping me grounded through some very difficult times and focused on the ultimate goal is much appreciated.
I am thoroughly satisfied with Mr. Breeland’s representation. I would enthusiastically recommend him and Breeland Injury Law to any business or individual seeking strong, effective, and results-driven legal counsel for a personal injury case in Austin, Texas.
Matt was recommended to me by one of the biggest personal injury firms in Austin. Over the course of my 6 month case, he guided me every step of the way and made the process very streamlined and straightforward. He always replied quickly and definitely helped manage my expectations. If you need personal injury legal advice, I couldn’t recommend Matt more highly.
I can’t say enough great things about Breeland Injury Law. From start to finish, Matt was incredibly attentive, professional, and genuinely cared about my case. He took the time to explain everything clearly, kept me informed every step of the way, and worked tirelessly to make sure I received the best possible outcome.
What truly stood out was his integrity—he even reduced his fee to ensure I could receive the full benefit of my settlement. That kind of compassion and dedication is rare.
If I ever need an injury lawyer again, Matt Breeland will be my first and only call. I highly recommend him to anyone looking for a skilled and trustworthy attorney who puts their clients first.
I was in a rear end accident and had several medical bills related to my neck. Even with issues from the medical providers and records, Matt was able to get a settlement that covered all my expenses and gives me a cushion for future expenses. He made the process easy for me.
I had an excellent experience working with Matt Breeland with Breeland Injury Law. He was knowledgeable, professional, and truly dedicated to helping me navigate my legal situation. From our first consultation, he took the time to explain everything clearly, ensuring I understood my options and the best course of action. His attention to detail, responsiveness, and commitment to my case gave me confidence and peace of mind throughout the process.
Beyond his expertise, Mr. Breeland was compassionate and genuinely cared about achieving the best outcome for me. He handled everything efficiently and kept me informed at every stage. I highly recommend Breeland Injury Law to anyone in need of a skilled and trustworthy attorney.
I can’t thank Matt Breeland enough for everything he did for me. From day one, he went above and beyond. always taking the time to explain every step, answer all my questions, and make sure I felt supported throughout the entire process. He truly cared about my well-being, not just the case, and made sure I got the best possible outcome. His professionalism, dedication, and compassion are unmatched. I would highly recommend him to anyone in need of an injury lawyer who will fight for you and genuinely take care of you.
Matt is an amazing attorney. He made the process of my accident smooth, and not only that, I had a second accident right after the first, and he handled both expediently and efficiently. He knows his stuff. He’s such a nice guy; he makes you feel comfortable. He responds to your texts/calls, and if you don’t understand something, he’ll explain it to you until you do. I put all my trust in him, and I’m glad I did; he’s more than an attorney—he’s a friend. I highly recommend Matt.
My husband and I were involved in a multi-car accident in 2022; after speaking to several law firms, we decided that Matt would represent us through the complicated legal landscape. What sets Matt apart from bigger law firms is the access and communication to speak to your actual attorney. We had a standing Wednesday appointment to speak to Matt regarding any questions, concerns, and expectations about our health and our case. As our case evolved to the nuances of personal injury Matt continued to go to bat for us against numerous law firms with unwavering conviction. He will give you an honest, unbiased opinion of your options and your choices regarding your case going forward and insert his expertise on possible outcomes. Matt is a genuine person who is deeply passionate about his clients and the law. If you are considering hiring an attorney, you can expect honesty, transparency, and fairness from Breeland Injury Law.
Truly one of the best experiences I’ve had with an attorney. Matt quite literally saved me from a terrible situation and gave me the best outcome. I cannot recommend him enough.
A friend of mine recommended Matt to me after being in a car accident. This was the first time I was in a car accident and I had no clue what I should do. I am glad that I had chosen Matt as my lawyer because he helped me along the whole way. While working on my case, I moved to another country, then moved back to the states. But Matt made everything very easy for me. I had full trust in him that he was doing the best for me and everything turned out great. Highly recommend Matt Breeland!
I was injured in a traffic accident as a pedestrian. After talking to a few lawyers, I decided to choose Matt for two reasons: 1) I couldn’t find any bad reviews of him online (now I understand why), and 2) he was incredibly patient listening and explaining to me the whole process of being involved in a personal injury case. I am not a US citizen, I was in the US working temporarily so I had no idea what was coming. Having someone on my side who truly cared and made everything easy simply meant the world to me. He was always available to answer my questions and the case turned out incredibly well. Choosing Matt has been one of the best decisions I have ever made, as he turned one of the most traumatic moments in my life into something manageable. I cannot thank him and recommend him enough.
A mutual friend referred me to Matt after a car accident that left me injured. I did some shopping around before I contacted Matt, and after we spoke I knew he was the right person to represent me. He was transparent, supportive, and communicative. When searching for a lawyer who specializes in injury law, you may come across some questionable characters. Thankfully, I found Matt, and he is not that. Matt brings integrity and sincerity to his work. He made it easy to communicate and was always accommodating to my schedule if I was busy. His persistence got me through the settlement process seamlessly and painlessly, with my settlement done just in time for the holidays. I’m thankful for how easy he made a stressful process.
Matt went above and beyond in my personal injury case. There weres several unexpected and unique twists and turns that popped up, and Matt never wavered. If you’re in need of high quality, attentive, and caring representation with attention to detail, I couldn’t recommend anyone more than Mr. Breeland. Huge thanks to Matt Breeland and his team!
I had to make my first insurance claim after a motorcycle accident with an uninsured motorist and quickly realized I couldn’t get what I needed myself. Breeland Injury law got me the maximum allowable. It took longer than I expected, but I am very pleased with the results. Matt worked hard to get me what I needed, and I’m very greatful.
I was very impressed with the level of service I received! Matt Breeland was my attorney. I had an injury (slip & fall) caused by negligence that was caught on video. They had a phone consultation with me and then we met face to face. They were very thorough and told me the very worst scenario and the best and also a typical outcome. They were very responsive and I even corresponded by text and phone calls with Matt (e-mails as well). There were some challenges on the way due to my personal situation, but they were very accommodating. I have had bad experiences with lawyers before (not responding to phone calls or emails); so it was very refreshing having the level of personal service I received. I felt that they were really my partner in getting a just settlement. I highly recommend Matt Breeland!
You don’t realize that you need a lawyer in life until something unexpected happens. After calling different lawyers i decided to pick Matt, he has good communication skills and will get back to you with any questions asked. I believe that Matt is someone who works hard and tries which in my experience is hard to find these days. I made the correct decision with being represented by Matt Breeland.
Matt Breeland is an AMAZING attorney. Not only was he considerate and consistent in his communication, but he went to bat for me! Although I hope I don’t have a need for him in the future, I would use him again and again!! j can’t recommend him enough.
I was in a motorcycle wreck July 2023 and was out of work for 4 months. I had never dealt with lawyers before. My case got referred to Mr. Breeland from Daniel Stark. There were some communication concerns but that may just be that I didn’t like being in the dark with so many unknowns but when I had questions Mr. Breeland was very patient with me and answered them to the best of his abilities. When my insurance and doctors tried to charge me AND demand money from the settlement amount Mr. Breeland did a great job getting that sorted out and did the same when my orthopedic sent debt collectors my way. Obviously I hope to never need an injury lawyer again but if that need arises again I’d trust Mr. Breeland again.
Matt is a brilliant attorney and very knowledgable in the field. I never had a doubt at any moment and he ensured that I understood the process and all my options. I believe I would have been in worse condition if he did not take care of me. No one wants to be in a car accident, but if this does happen to you, pick up the phone and call as you will be in good hands.
Many years of experience pairs nicely when you are cared for like a family member. The wealth of knowledge that Matt has certainly will make you feel comfortable moving forward towards the right direction.
My overall experience if i can rate it more than 5 stars i would. Don’t waste time reviewing others, just pick up the phone and see for yourself.
We are ever so grateful to have worked with Matt Breeland to help us with a personal injury issue. The case was resolved to our great satisfaction and maybe more importantly, Matt was attentive to our needs, responsive to our questions, and not once did we feel that we were “just another client”. I hope we won’t ever again require such services, but if we do, we know who we will be calling!
Matt was honestly the best lawyer I could have hoped for. My case was complicated and Matt was understanding, patient, and took care of everything for me. Everything turned out so much better than I could have even possibly imagined. I highly recommend his services and would not hesitate to call him again.
Matt is very kind and hardworking man who diligently handled my case and made sure that everything was taken care of.
Matt Breeland is not only great at what he does, he also won’t dance around, lie to you, or ghost you. He took on our case, after it just hanging in the air and our lawyer ghosted us. He made it his goal to help us and get us some justice! And boy did he deliver and also in a nick of time.
Very professional, amazing communication, hands on and zero worries for us. Could not have felt more comfortable. We are very thankful to everything he has done for us. Tha k you, from the bottom of my heart!
If it wasn’t for Matt I wouldn’t have gotten anything. He worked really hard getting a settlement for me. If at anytime you want to talk to him, he is there for you. He explains everything to you. With me sometimes two or three times before it would sink in for Me. But he would do it over an over for me if I needed it. Matt is a wonderful attorney to work with.
I’ll start with a little pretext, I was riding my motorcycle on the access road of 183 on July 20th and a car jumped across 3 lanes of traffic and side swiped me. I broke 4 out of 5 metatarsal bones in my right foot. Initially I went to Matt while he was still with FVF law, but while my case was still in initial phases Matt decided to go off on his own and open up his own practice. After being given the choice to stay with FVF or go with him it was an easy decision to stay with Matt especially remembering the fact that he also helped my friend win a HUGE settlement years ago.
Anyways after breaking my foot and deciding to stay with Matt on his independent venture Matt was the kind of lawyer I needed him to be from the very moment we started things at FVF to the final delivery of my settlement. Matt never let me feel out of the loop and he was very responsive to my outreach even when I’d text him on days/times you wouldn’t always expect a working professional to respond. Matt’s ability to keep me as a client level headed and informed through the whole process was what made him good and his attention to detail and personal touch are what makes great. I would recommend him to anyone looking for an injury lawyer!
Matt Breeland is awesome! He’s a straight shooter that gets back to you right away. It was always easy to reach him, which can be a bit of a challenge with some attorneys. I would recommend having him handle your case!
After waiting for seven months for the at fault party’s insurance to finalize only to be offered an amount less than my deductible, I reached out to one of the “big” injury firms and was referred to Matt. I am so glad I made that call! Professional, highly communicative, and an easy demeanor reduced my stress around the situation greatly. I was hoping to get reimbursed for my out-of-pocket expenses around the rental car, lost wages, and vehicle replacement. In the end, I received over three times that amount. I hope not to need his services again, but I will surely be recommending him to anyone I know who does.
My first time involved in a medical injury case and Matt could not have handled it better, definitely recommend!
Matt did an outstanding job handling my injuries claim from the beginning to the end. His priority was how I could get I the best treatment . Always kept communication wide open, honest and very diligent. Very professional
Very professional attorney who got great results for my case. Would highly recommend!
he’s great! He helped me deal with a very difficult insurance company. He’s had much more profitable cases than mine, but he still helped. His negotiation skills are stellar and as busy as he is he still manages to be very communicative. He’ll make sure you get the medical treatment you need and he will also get to know you.
Mr. Breeland was very communicative, very professional. Great with his time management. As well being up front about everything from price to how long it could take. Made me feel like my case was very important to him as well.
Matt did a phenomenal job for me. His expertise, precision, and dedication was beyond what was expected. I hope I never have to deal with a situation like this again, but if I do; I at least know I have the best representation in town with Matt!
Outstanding Attorney And Staff. They Helped Me Immensely,Ensuring That I Received All The Necessary Treatment I Needed For My Recovery.
Matt was very professional, friendly and was assuring throughout the whole process. I could not recommend him enough!
After my car accident my father researched online for the top attorneys in Central Texas. Breeland Injury Law popped up. I gave him a call and the entire case was a pleasant experience. He and his team were very accessible and answered all of my questions and kept me abreast of every step in the process. I would definitely recommend Breeland Injury Law.
Matt and his team are amazing, they are extremely understanding of what their clients are dealing with and go above and beyond to get the best results possible. I highly recommend them for any of your personal injury needs!
Matt Breeland’s honesty and genuine care for me, his client, impressed me in all ways, and his many successes speak clearly of his legal talents. He and his office are easy to work with, and are gentle, even when you don’t understand the process. I highly recommend Matt Breeland.
Count On Austin
Attorney Matt Breeland
Contact Breeland Injury Law
Fields marked with an * are required